

MoodWallet: Money Management
Jomo Labs
- 4.3
- 41.00 Reviews
- 10.00K
- Downloads
- Free
- Price
Screenshots
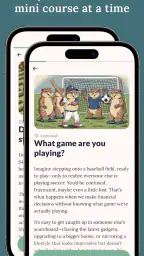
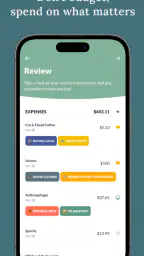
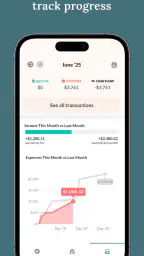
MoodWallet: Money Management Pros and Cons
Pros
- Clear overview of income, expenses, and available balance
- Useful budgeting tools for tracking spending habits
- Simple interface makes daily money logging approachable
- Helps organize financial goals in one convenient place
- Suitable for users who want a lightweight expense tracker
Cons
- Some advanced features may require a paid subscription
- Manual transaction entry can become time-consuming
- Limited usefulness without consistent and accurate data input
- May lack specialized tools for complex financial planning
- Privacy-conscious users should review its data handling policies
 Analysis by All-app
Money management usually becomes hardest when I am tired, rushed, or already worried about spending. That is the problem MoodWallet: Money Management tries to address. It is a finance app from Jomo Labs built around the emotional side of everyday purchases, rather than asking me to maintain a detailed budget for every category. In my experience, that makes it feel less like a spreadsheet and more like a short pause before I spend.
The idea is appealing, especially for someone who has downloaded budgeting tools before and abandoned them after a few days. MoodWallet is free to install, rated for Everyone, and available for Android devices running version 7.0 or later. It has reached over ten thousand installs and holds a 4.3 average from around 150 ratings, which suggests a modest but generally positive user base. There are also in-app purchases ranging from $6.99 to $89.99 per item, so I would still pay attention to the purchase screen before committing to anything beyond the free experience.
How MoodWallet feels to use when attention and energy vary
When my attention or energy is low, I find it helps to make the task smaller rather than demand a full review of my finances. A quick, private check-in can still capture the feeling behind a purchase, while a longer review can wait until I’m rested. That makes consistency more realistic—and leads to a useful question: which everyday situations give MoodWallet enough room to help?
Readability and navigation are strongest when the task stays small
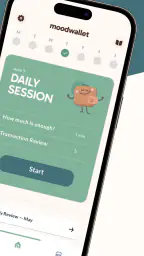
The most useful quality here is the app’s attempt to reduce the amount of mental work involved in reflecting on a purchase. Traditional budgeting apps often lead with balances, categories, charts, recurring transactions, and setup forms. Those tools can be valuable, but they also create a lot of visual and cognitive noise. MoodWallet takes a gentler route: it encourages me to connect spending with how I feel and whether the purchase actually helped.
That approach matters for people who find dense financial interfaces intimidating. Someone with limited financial experience may understand a question about a recent purchase more easily than a request to build a complete monthly plan. Likewise, a user dealing with anxiety may be more willing to consider one decision at a time than face a dashboard full of warnings and totals. The app’s central concept gives the interaction a clear purpose instead of making me learn a whole budgeting system first.
I found that this kind of navigation works best when I use it immediately after a purchase or during a calm review session. It is less useful if I expect it to reconstruct my entire financial life automatically. MoodWallet is better understood as a reflective spending companion than as a full accounting record. That distinction is important because it prevents disappointment and helps me use the app for the job it appears designed to do.
For readability, short prompts and a focused decision flow are preferable to long explanations. They can also help users who have difficulty sustaining attention, including people who are easily distracted by multiple menus. The trade-off is that a simpler interface may provide less context at a glance. A person who wants to compare several months, inspect detailed categories, or reconcile every transaction may find a conventional finance dashboard more informative.
More Reads From Our News Desk

Switching to the Xbox App: What Changes in Your Gaming Routine

Coloring & Learn Review: A Satisfying Canvas, Cluttered Menus

Microsoft 365 Copilot on Your Phone: Who Actually Needs It?

Mafia City: The Crime Saga That Outshines Its Rivals

Woodturning Transformed: How OS Updates Enhance Your Craft

How Tiles Hop EDM Rush Redefines Music Gaming
I would recommend starting with one narrow habit rather than trying to use every part of the experience. For example, I might open the app after an unplanned online order and record whether I felt excited, stressed, bored, or pressured. After several entries, the value is not in a single answer; it is in noticing whether certain situations repeatedly lead to spending that I later question. This workflow makes the app easier to understand and avoids turning self-reflection into another chore.
Motor and sensory considerations depend on the surrounding phone setup
A lightweight reflection process can be friendlier to users with limited dexterity than a finance app that demands extensive data entry. Fewer fields generally mean fewer taps, less typing, and less precision work. That is useful when hand movement is painful, when tremors make small controls difficult, or when fatigue makes a long form unrealistic. I would still test the app personally with the device’s preferred text size, display scaling, and touch settings, because comfort can vary considerably between phones.
The emotional focus may also suit users who process information better through plain language than through graphs. A chart can tell me that spending increased, but a simple prompt may help me recognize that I shop when overwhelmed or use purchases as a reward after a difficult day. That is a different kind of accessibility: not a technical feature, but a presentation style that may make financial reflection feel more understandable.
At the same time, I would not assume that a calm design automatically works for every sensory profile. Some people need strong contrast, larger controls, reduced motion, screen-reader-friendly labels, or a very predictable focus order. I would check the app on the individual device and with the accessibility settings I rely on before making it part of an essential money routine. The available information establishes the app’s age rating and operating-system requirement, but it does not make a formal accessibility certification claim, so personal testing remains sensible.
There is also a sensory advantage to using the app away from a busy environment. If I am standing in a noisy shop, switching between apps, or trying to make a purchase quickly, emotional prompts can feel like one more demand. In a quiet moment, the same prompts are easier to answer honestly. This is why I see MoodWallet as a tool for deliberate check-ins rather than something I would necessarily use during every transaction.
One practical tip is to avoid opening it while already overstimulated unless the goal is simply to postpone a purchase. If I cannot comfortably read or process the prompt, I can treat that discomfort as useful information and wait before deciding. That makes the app part of a pause routine instead of another source of pressure. It is a small but meaningful distinction for users whose concentration changes with noise, stress, pain, or fatigue.
Situational access makes the app more useful than its simplicity first suggests
MoodWallet can fit several everyday situations where a full budget is too demanding. Imagine I have had a difficult workday and start browsing shopping apps late at night. I add an item to my basket, then pause to consider what I am feeling. If the answer is loneliness or frustration rather than a genuine need, the moment of reflection may be enough to close the app. Even if I still buy the item, recording the context can help me understand the pattern later.
Another useful situation is irregular income. A strict monthly budget can feel misleading when pay varies or expenses arrive unpredictably. MoodWallet does not replace planning, but its focus on spending decisions can still help me identify purchases that are emotionally driven. I can use that insight alongside a bank account, a bill calendar, or a separate savings method instead of forcing every financial need into one application.
The app may also suit couples or families who struggle to discuss spending without blame, although I would use care here. A personal reflection tool can help me describe my own habits more clearly, but it should not become a way to monitor or judge another person. For someone with a support worker, trusted friend, or partner, a few observations could provide a calmer starting point for a conversation about triggers and priorities.
People with attention-related difficulties may appreciate the low barrier to starting. Rather than waiting for the perfect time to organize receipts and categories, I can record one recent decision while it is still fresh. The realistic goal is consistency, not completeness. A short check-in that I actually repeat is more valuable than an elaborate budget that I avoid.
There is a useful trade-off for people who are visually impaired or who prefer audio-based interaction. A simple text-led process may be easier than a chart-heavy alternative, but the actual experience still depends on how labels, controls, and prompts behave with the device’s assistive technology. I would not choose MoodWallet solely on the assumption that less visual complexity guarantees better screen-reader access. I would try the key workflow first: opening a reflection, entering a response, and reviewing it later.
Situational access also includes device age. The minimum requirement of Android 7.0 makes the app potentially usable on older Android hardware, which is helpful for people who cannot replace a phone frequently. The current version is 2.12.0, so I would keep the app updated when the device allows it, particularly for compatibility and stability. A person using iOS should check the relevant store page and device requirements before planning around it, rather than assuming the Android requirement applies everywhere.
Remaining barriers: reflection is not the same as money control
The biggest limitation is scope. MoodWallet can help me notice why I spend, but it should not be my only system for bills, debt repayment, account balances, tax records, or shared household accounting. If I need exact transaction tracking, automatic categorization, forecasting, or detailed reports, a conventional budgeting app or a spreadsheet will probably be a better fit. The emotional perspective is valuable, but it does not remove the practical work of knowing what money is available.
There is also a risk of over-personalizing financial problems. Not every difficult purchase is caused by mood. Prices, low income, emergencies, family responsibilities, and unexpected bills can shape spending just as strongly. I would use the app to explore patterns, not to blame myself for circumstances outside my control. A good reflection should lead to a realistic adjustment, such as removing a tempting shopping shortcut or planning a small comfort expense, rather than harsh self-criticism.
The in-app purchase range deserves attention for another reason: users who are trying to reduce financial stress may be especially sensitive to unclear upgrade decisions. The app is free to install, but optional purchases can still affect whether it remains comfortable for someone on a tight budget. I would explore the free experience first and only consider paying if the additional value is clear, affordable, and genuinely useful to my routine.
Another barrier is motivation. A reflective app cannot force me to record a purchase honestly, and its benefits may be subtle rather than immediate. Someone looking for an instant spending lock, automatic bank intervention, or a strict accountability system may find it too gentle. In that situation, a different tool with concrete limits or automated transaction tracking would be more appropriate.
Privacy and emotional comfort are personal considerations too. Spending habits can reveal sensitive information about stress, relationships, and coping strategies. I would read the app’s current privacy details before entering anything I would not want stored, and I would avoid using it as a substitute for professional support if spending is connected to serious distress, compulsive behavior, or a crisis. The app can support awareness, but it is not therapy or financial advice.
For users who share a phone, accessibility may also become situationally complicated. A private reflection can be difficult if notifications or open screens are visible to someone else. I would choose a quiet, private time to use it and avoid writing details that could create a safety problem. This matters particularly for people whose finances are monitored by a controlling partner or family member. A helpful tool should never increase personal risk.
Three practical ways I would get more from it
First, I would use a “before and after” routine for purchases that are easy to rationalize. Before buying, I would note the feeling and the reason. Later, I would compare that with how the purchase actually felt. The useful insight is often the gap between anticipated relief and real satisfaction. This is more informative than simply labeling a purchase good or bad.
Second, I would review entries by situation rather than by price alone. A pattern tied to late-night scrolling, social pressure, or post-work exhaustion suggests a different solution from a pattern tied to genuine household needs. The response might be changing a routine, adding a waiting period, or discussing expectations with someone else. MoodWallet’s emotional angle becomes most practical when it leads to a specific environmental change.
Third, I would pair it with one external safeguard. That could be a separate bill calendar, a weekly account check, or a simple spending limit for discretionary purchases. The point is not to duplicate every feature in another app; it is to cover the gap between emotional awareness and financial accuracy. This combination lets MoodWallet do what it does best without asking it to become a complete banking system.
I would also keep the reflection language nonjudgmental. Instead of writing that I was “bad” for buying something, I would describe the trigger, the expectation, and the result. This makes the record more useful and more accessible to people who shut down when financial tools sound scolding. It also makes it easier to share a pattern with a trusted person without turning the conversation into an argument.
My inclusive verdict for different kinds of users
After using MoodWallet as a focused reflection tool, I see a thoughtful option for people who feel overwhelmed by traditional budgeting. Its strongest contribution is not accounting precision; it is helping me slow down and connect spending with real-life context. That can make financial reflection more approachable for users with limited attention, fluctuating energy, anxiety around numbers, or little patience for complex setup.
I would recommend it to someone who repeatedly makes impulse purchases, starts budgets but does not maintain them, or wants to understand the emotional triggers behind spending. I would also suggest it to a user who needs a gentle first step before adopting a more detailed financial system. The free entry point makes experimentation easier, while the Everyone rating and older Android compatibility broaden its potential audience.
I would steer a different user toward a more conventional finance app if they need automatic records, detailed category analysis, shared accounts, debt schedules, or strict spending controls. I would also be cautious if the person has accessibility needs that depend on confirmed screen-reader behavior, specialized contrast support, or a particular input method. In those cases, direct testing should come before relying on the app.
Jomo Labs has created something more specific than a basic expense tracker: a way to examine the moment behind a purchase. That focus will not solve every money problem, and it may feel too soft for users who want hard limits. For me, though, the best use is clear: use MoodWallet to understand spending patterns, then pair that insight with a practical system that protects the essentials. When used in that role, it offers a considerate and accessible starting point without pretending that awareness alone is a complete financial plan.
Frequently Asked Questions
What is MoodWallet: Money Management, and what can I use it for?
MoodWallet: Money Management is designed to help you organize everyday finances in a more personal and approachable way. You can use it to record income and expenses, review spending habits, manage categories, and keep track of your financial progress. Its mood-focused approach may also help you reflect on how emotions influence purchases, making it useful for users who want more awareness rather than only a basic expense list.
Is MoodWallet suitable for beginners who have never used a budgeting app?
Yes, MoodWallet can be a practical starting point for beginners because the main idea is to make money tracking easier to understand and less intimidating. New users can generally begin by entering regular income, adding common expense categories, and reviewing summaries over time. However, the usefulness of the app depends on consistently recording transactions and taking time to understand its available settings.
Does MoodWallet connect directly to my bank account or financial institution?
Before downloading, users should check the current app description and privacy information to confirm whether bank synchronization is supported in their country and on their device. Some money-management apps rely entirely on manual entries, while others offer account connections through third-party services. If MoodWallet requires manual tracking, it may provide more control, but it also means your records will only be accurate when you update them regularly.
Is my financial information safe when using MoodWallet?
You should review MoodWallet’s privacy policy, permissions, and data-handling details before entering sensitive financial information. Avoid assuming that a budgeting app offers bank-level protection unless this is clearly explained by the developer. It is also wise to use a strong device passcode, keep the application updated, and avoid storing unnecessary account numbers, passwords, or other confidential details inside notes or transaction descriptions.
Is MoodWallet: Money Management free to download, and are there in-app purchases?
The application’s download price, advertising model, and premium features can change with updates, so check the Google Play Store or Apple App Store listing before installing it. Some features may be available at no cost while advanced tools, customization, cloud backup, or an ad-free experience may require payment. Carefully read subscription terms, renewal conditions, and trial details before confirming any purchase.


